Associates for Insurance Services
Landlord & Rental Dwelling Insurance
Dwelling fire and landlord coverage for rental houses, flips and managed properties in North and South Carolina.
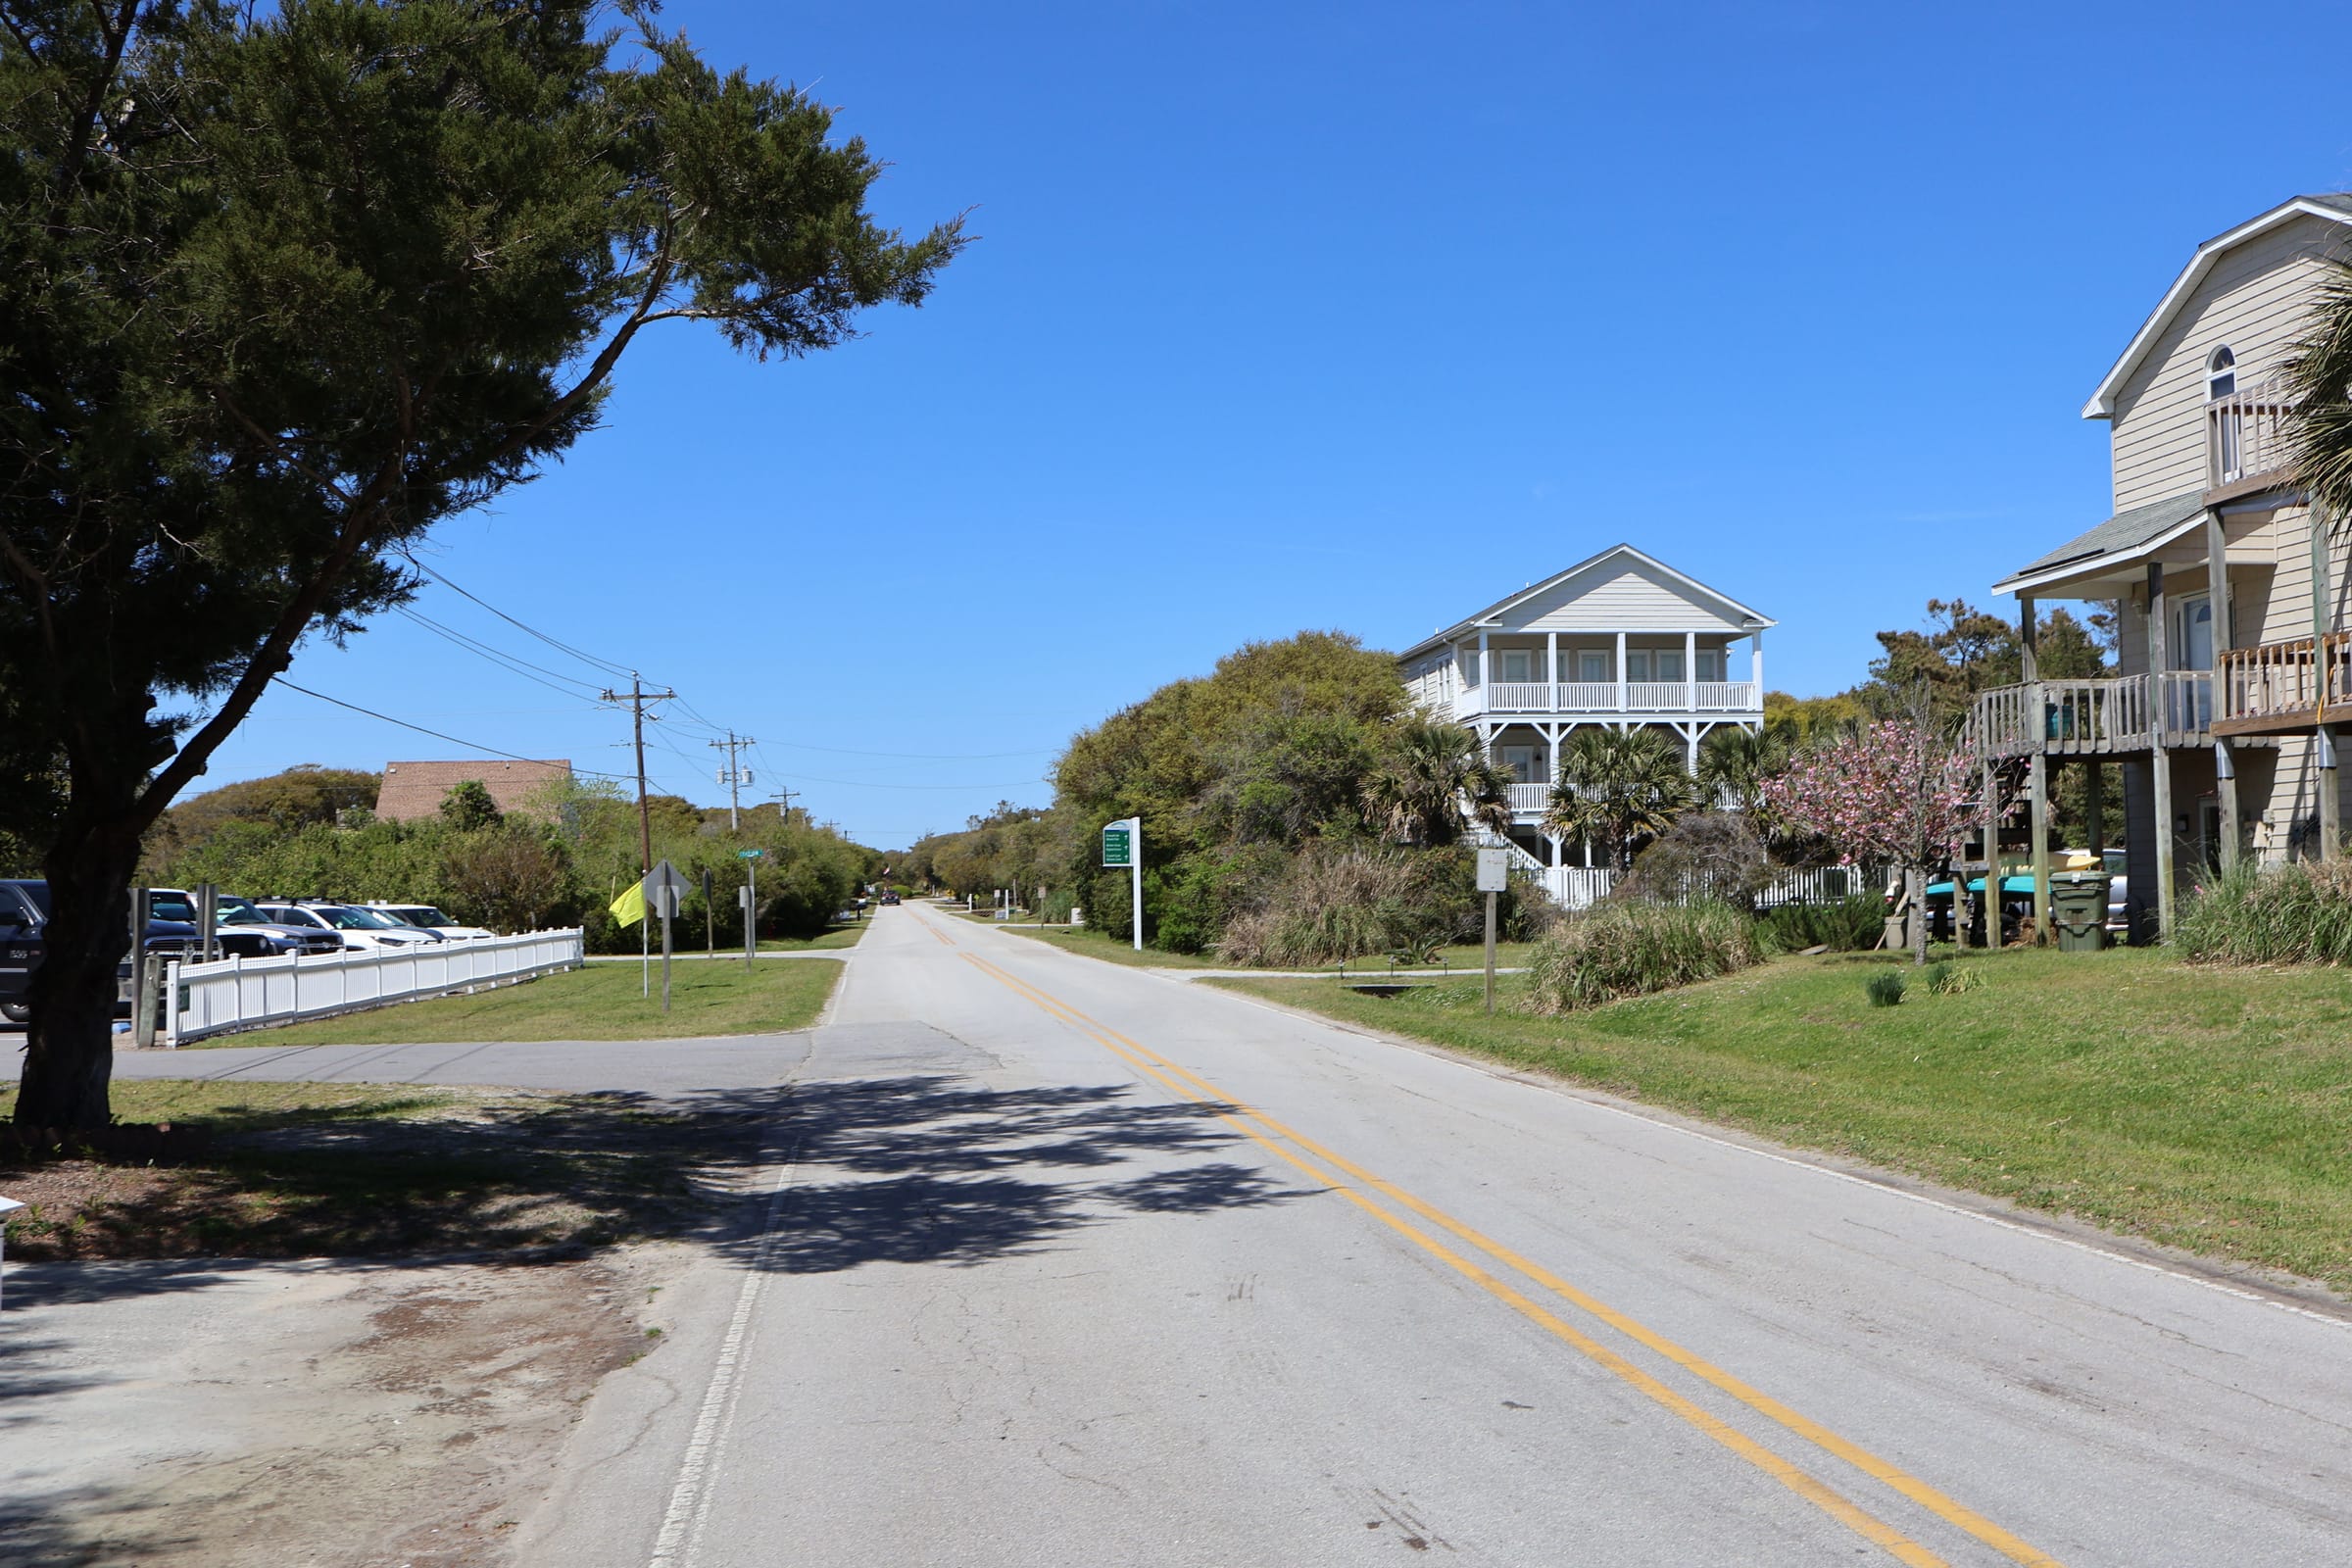
Coast Guard Road, Emerald Isle. Photo: DiscoA340, CC BY-SA 4.0
What landlord & rental dwelling insurance covers
A rental dwelling policy, often called a dwelling fire or landlord policy, covers a house or unit you own and rent to others: the structure, the landlord-owned contents, loss of rental income after a covered loss, and your liability as the owner. A house you are renovating to sell is written differently again, for the months it sits empty with a crew in it. A homeowners policy written for an owner who lives there is the wrong form for any of these.
Why it matters
A homeowners policy on a rented house can leave the owner without the coverage they assume is there, and a vacant house under renovation is excluded by most policies after a set number of days. The loss-of-rents piece is also the one owners forget until the property is unrentable for a season.
Who it is for
Landlords with one house or a dozen anywhere in North Carolina; investors closing on a rental and the agents and lenders who send them; house flippers and property managers in North and South Carolina, including the Greenville area; owners of a rental in either Carolina who have outgrown the homeowners policy it started on.
Here, specifically
Tell us how each property is used: long-term tenant, short-term rental, vacant during a renovation, or managed for someone else. Each is written differently. Flood is a separate policy for every one of them, and on the coast the wind and hail deductible applies to a rental house exactly as it does to the one you live in.
What a policy can include
- Dwelling fire (landlord) coverage
- Landlord contents and furnishings
- Loss of rental income
- Premises liability
- Vacant and renovation (flip) coverage
- Property manager and portfolio programs
How a quote goes
- 01
A conversation first
What you are protecting, how it is used, and what has changed since the last policy was written.
- 02
We look at the options available
Not every insurer writes every risk. We identify the options that fit the property, the vehicle or the business, and compare them.
- 03
We read for gaps
Deductibles, exclusions and limits, not just the headline number, so nothing surprises you later.
- 04
Plain English, zero pressure
We walk you through what each option does and leave the decision with you.
Questions we get about landlord & rental dwelling insurance
Do you write landlord policies in South Carolina?
I am renovating a house to sell it. What policy does it need?
Information is general in nature and may not reflect your specific situation. Contact us for guidance on your own policy.
Let's talk about your landlord & rental dwelling insurance.
A conversation about what you have and what your options look like, with zero pressure.