Associates for Insurance Services
Business & Contractor Insurance
General liability, workers' comp, commercial auto and property for landscapers, small contractors, commercial buildings, convenience stores, restaurants and taverns.
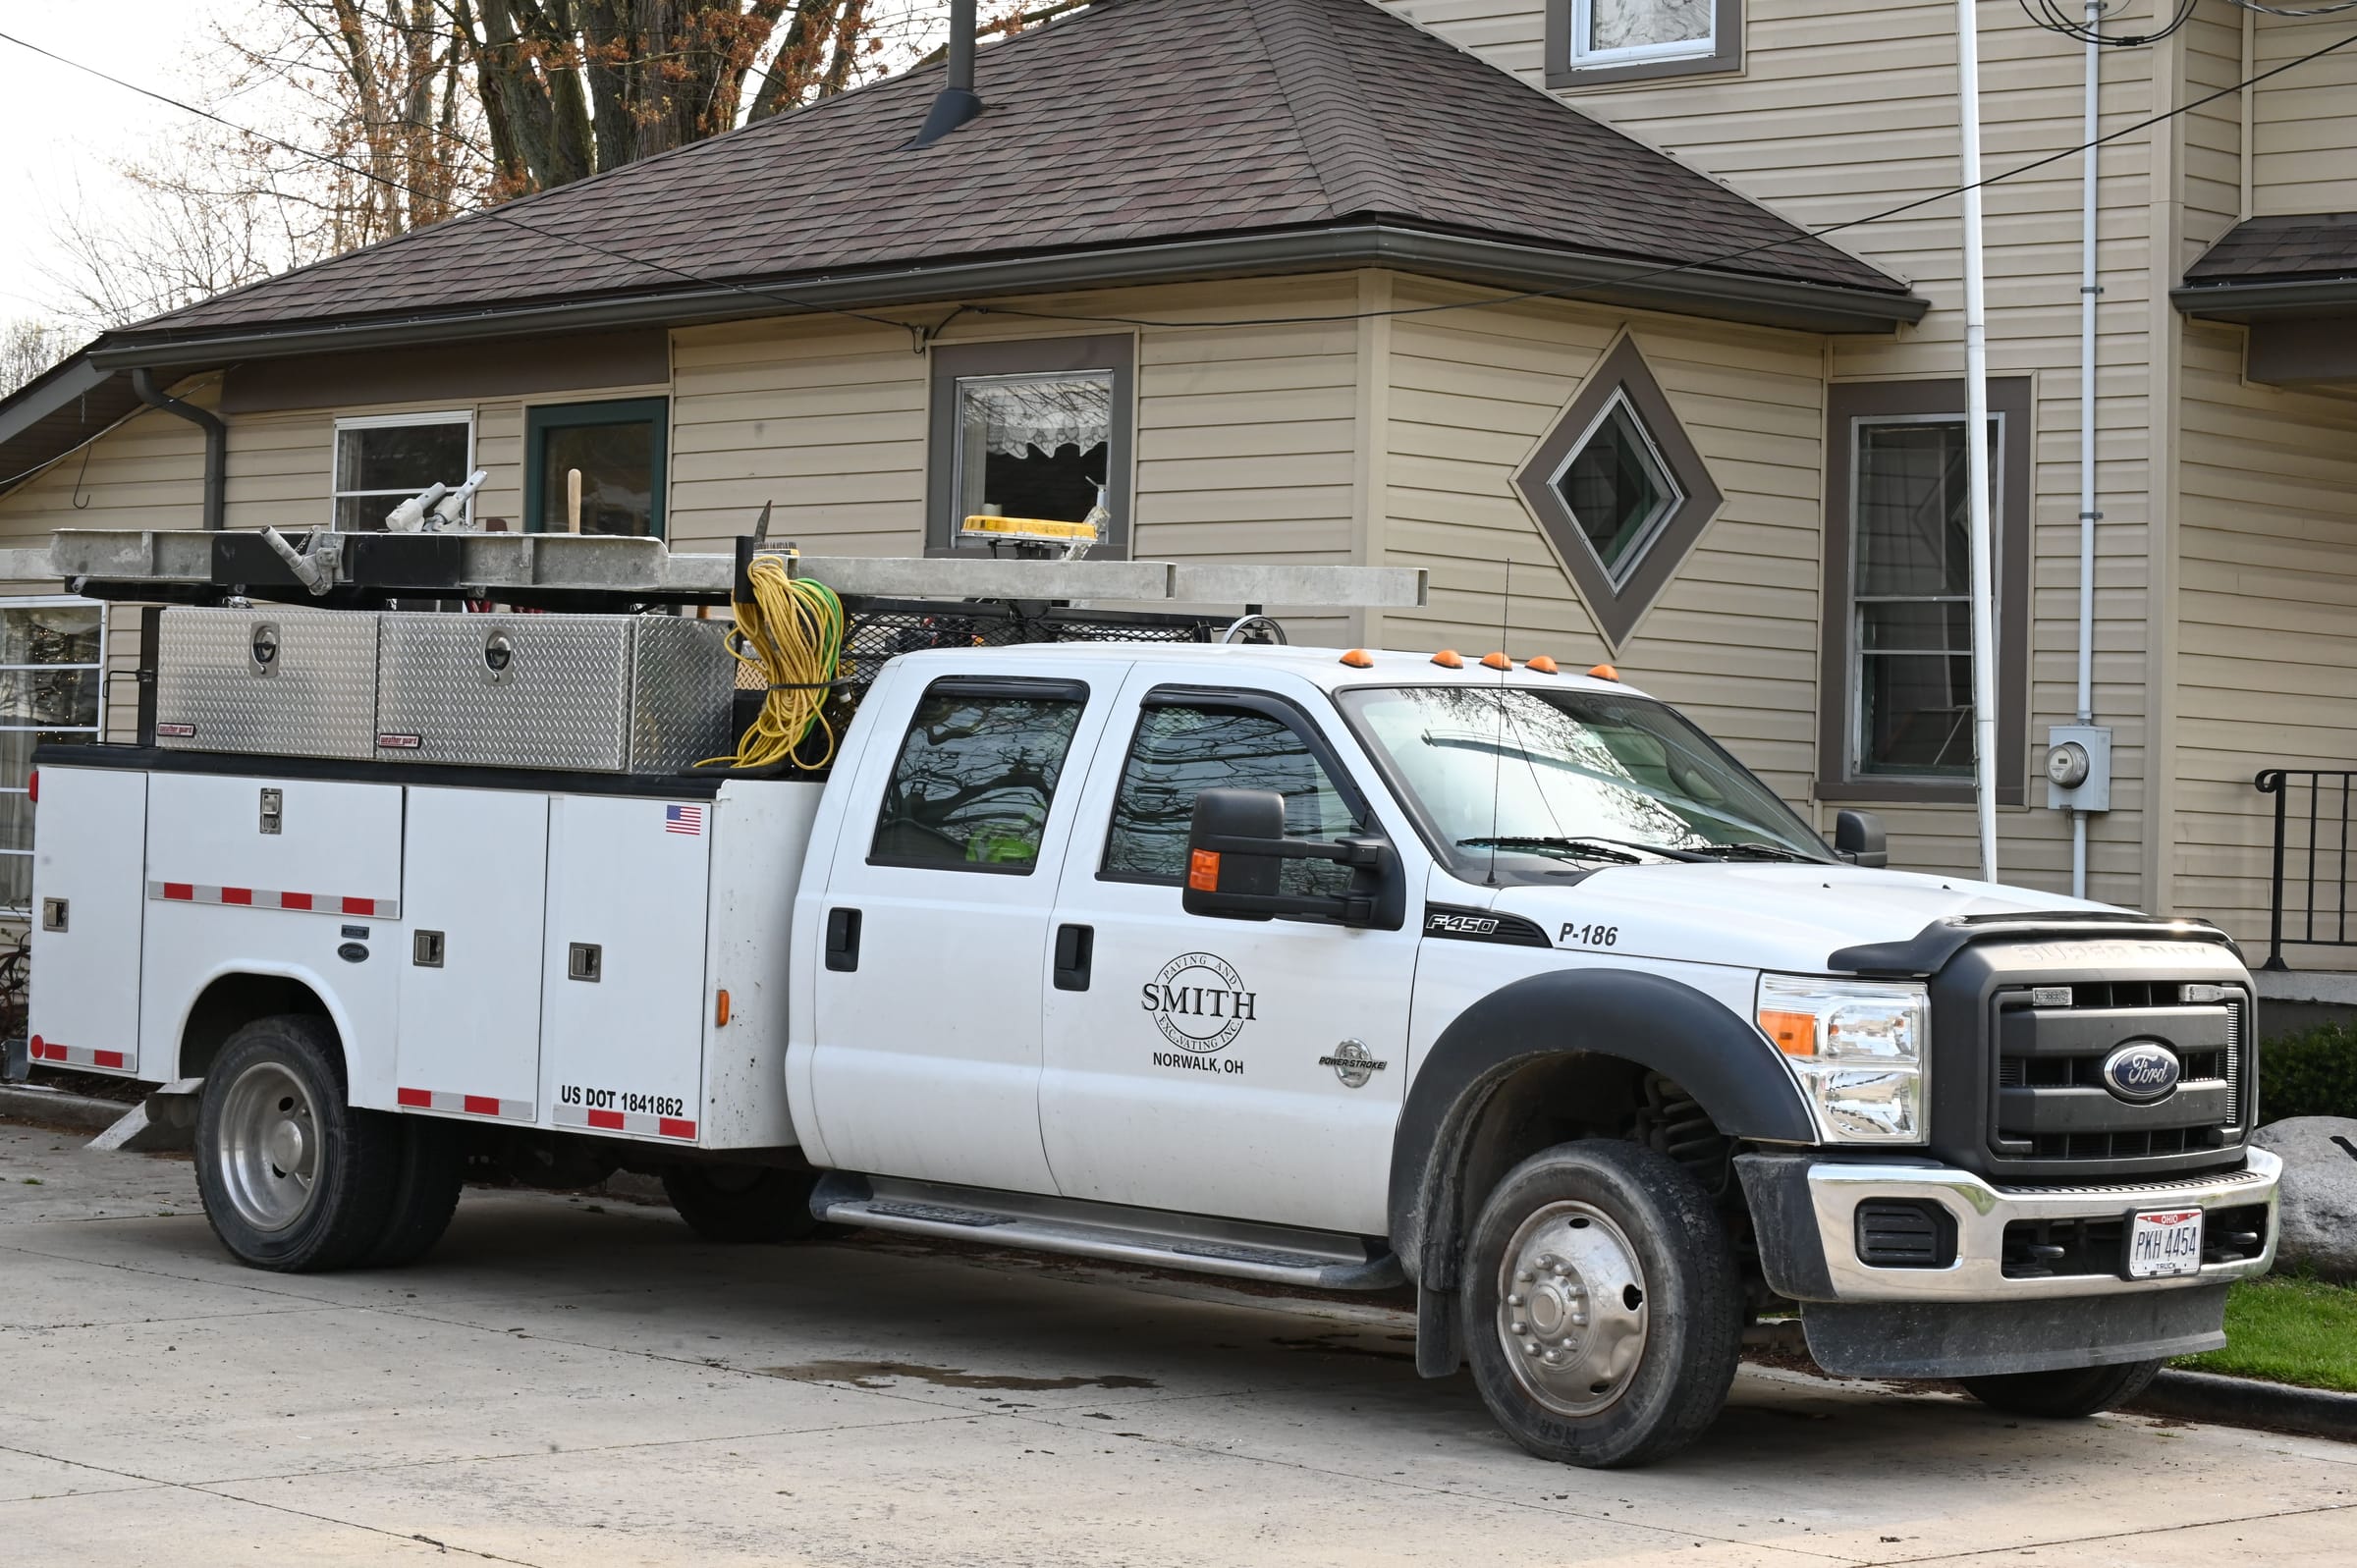
A service-body work truck. Photo: Jzadeh, CC BY-SA 4.0
What business & contractor insurance covers
Associates For Insurance Services helps plumbers, electricians, HVAC companies, landscapers, painters, excavators, general contractors and other trades find commercial insurance options. The core of a contractor's program is general liability, workers' compensation, commercial auto for the trucks and vans, and coverage for tools and equipment. The agency also writes commercial buildings, convenience stores, restaurants and taverns, with commercial auto for the vehicles. The details depend on the trade or the business, where the work is and whether you hire subcontractors.
Why it matters
A general contractor or a property owner will often ask for a certificate of insurance before you start a job, and a landlord or lender will ask a store or a tavern for proof of coverage before the lease is signed. Having the right coverage in place makes that request a two-minute task rather than a lost bid, and it means a claim is handled under a policy that was written to respond to your business.
Who it is for
Landscapers, HVAC companies, plumbers, electricians, painters, excavators, general contractors and other small contractors, from a one-truck operation to a crew with employees; owners of commercial buildings; convenience stores; restaurants and taverns, in North and South Carolina.
Here, specifically
Carteret County has 2,249 employer establishments (U.S. Census Bureau QuickFacts, 2023), and much of the work along the coast is building, repairing and maintaining property that sees salt, wind and water. Tell us which counties you pull permits in, whether you use subcontractors, and what equipment travels with the crew. For a store or a tavern, tell us about the building, the hours, whether you sell alcohol and who drives for the business; each of those changes how the program is written.
What a policy can include
- General liability
- Workers' compensation
- Commercial auto
- Commercial buildings and property
- Tools and equipment (inland marine)
- Convenience stores, restaurants and taverns
- Certificates of insurance for your jobs
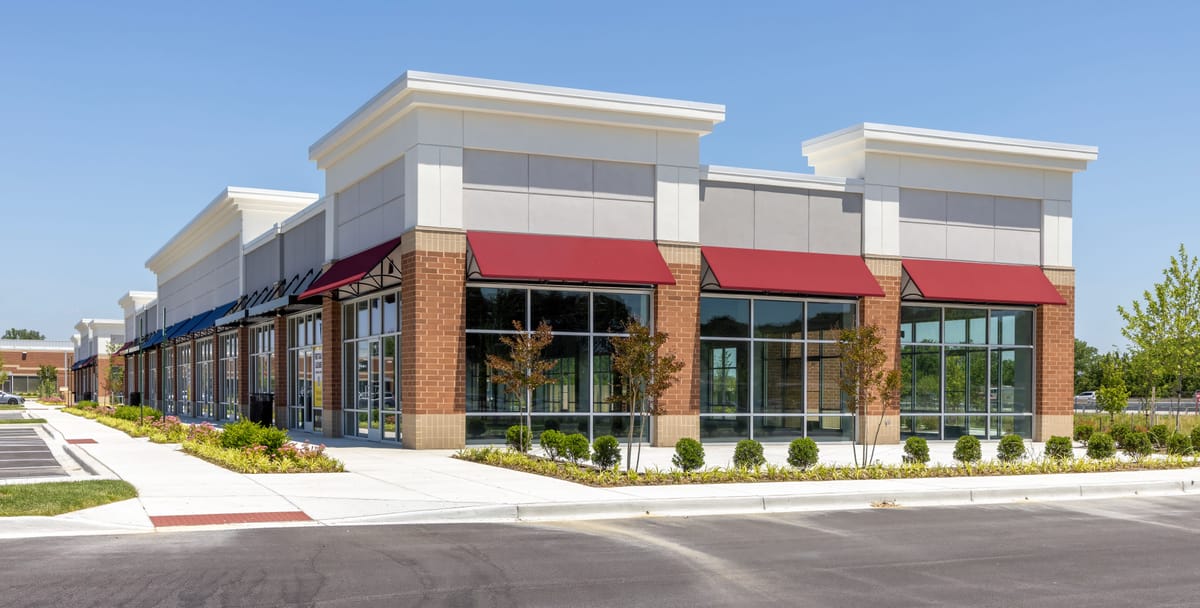
A newly built strip plaza, before its first tenants. Photo: Acroterion, CC BY-SA 4.0
How a quote goes
- 01
A conversation first
What you are protecting, how it is used, and what has changed since the last policy was written.
- 02
We look at the options available
Not every insurer writes every risk. We identify the options that fit the property, the vehicle or the business, and compare them.
- 03
We read for gaps
Deductibles, exclusions and limits, not just the headline number, so nothing surprises you later.
- 04
Plain English, zero pressure
We walk you through what each option does and leave the decision with you.
Questions we get about business & contractor insurance
Do you write businesses other than contractors?
Do I need workers' compensation?
Information is general in nature and may not reflect your specific situation. Contact us for guidance on your own policy.
Let's talk about your business & contractor insurance.
A conversation about what you have and what your options look like, with zero pressure.