Associates for Insurance Services
Coastal Home Insurance
Homeowners coverage for houses on and around Bogue Sound, with the wind, hail and flood questions answered up front.
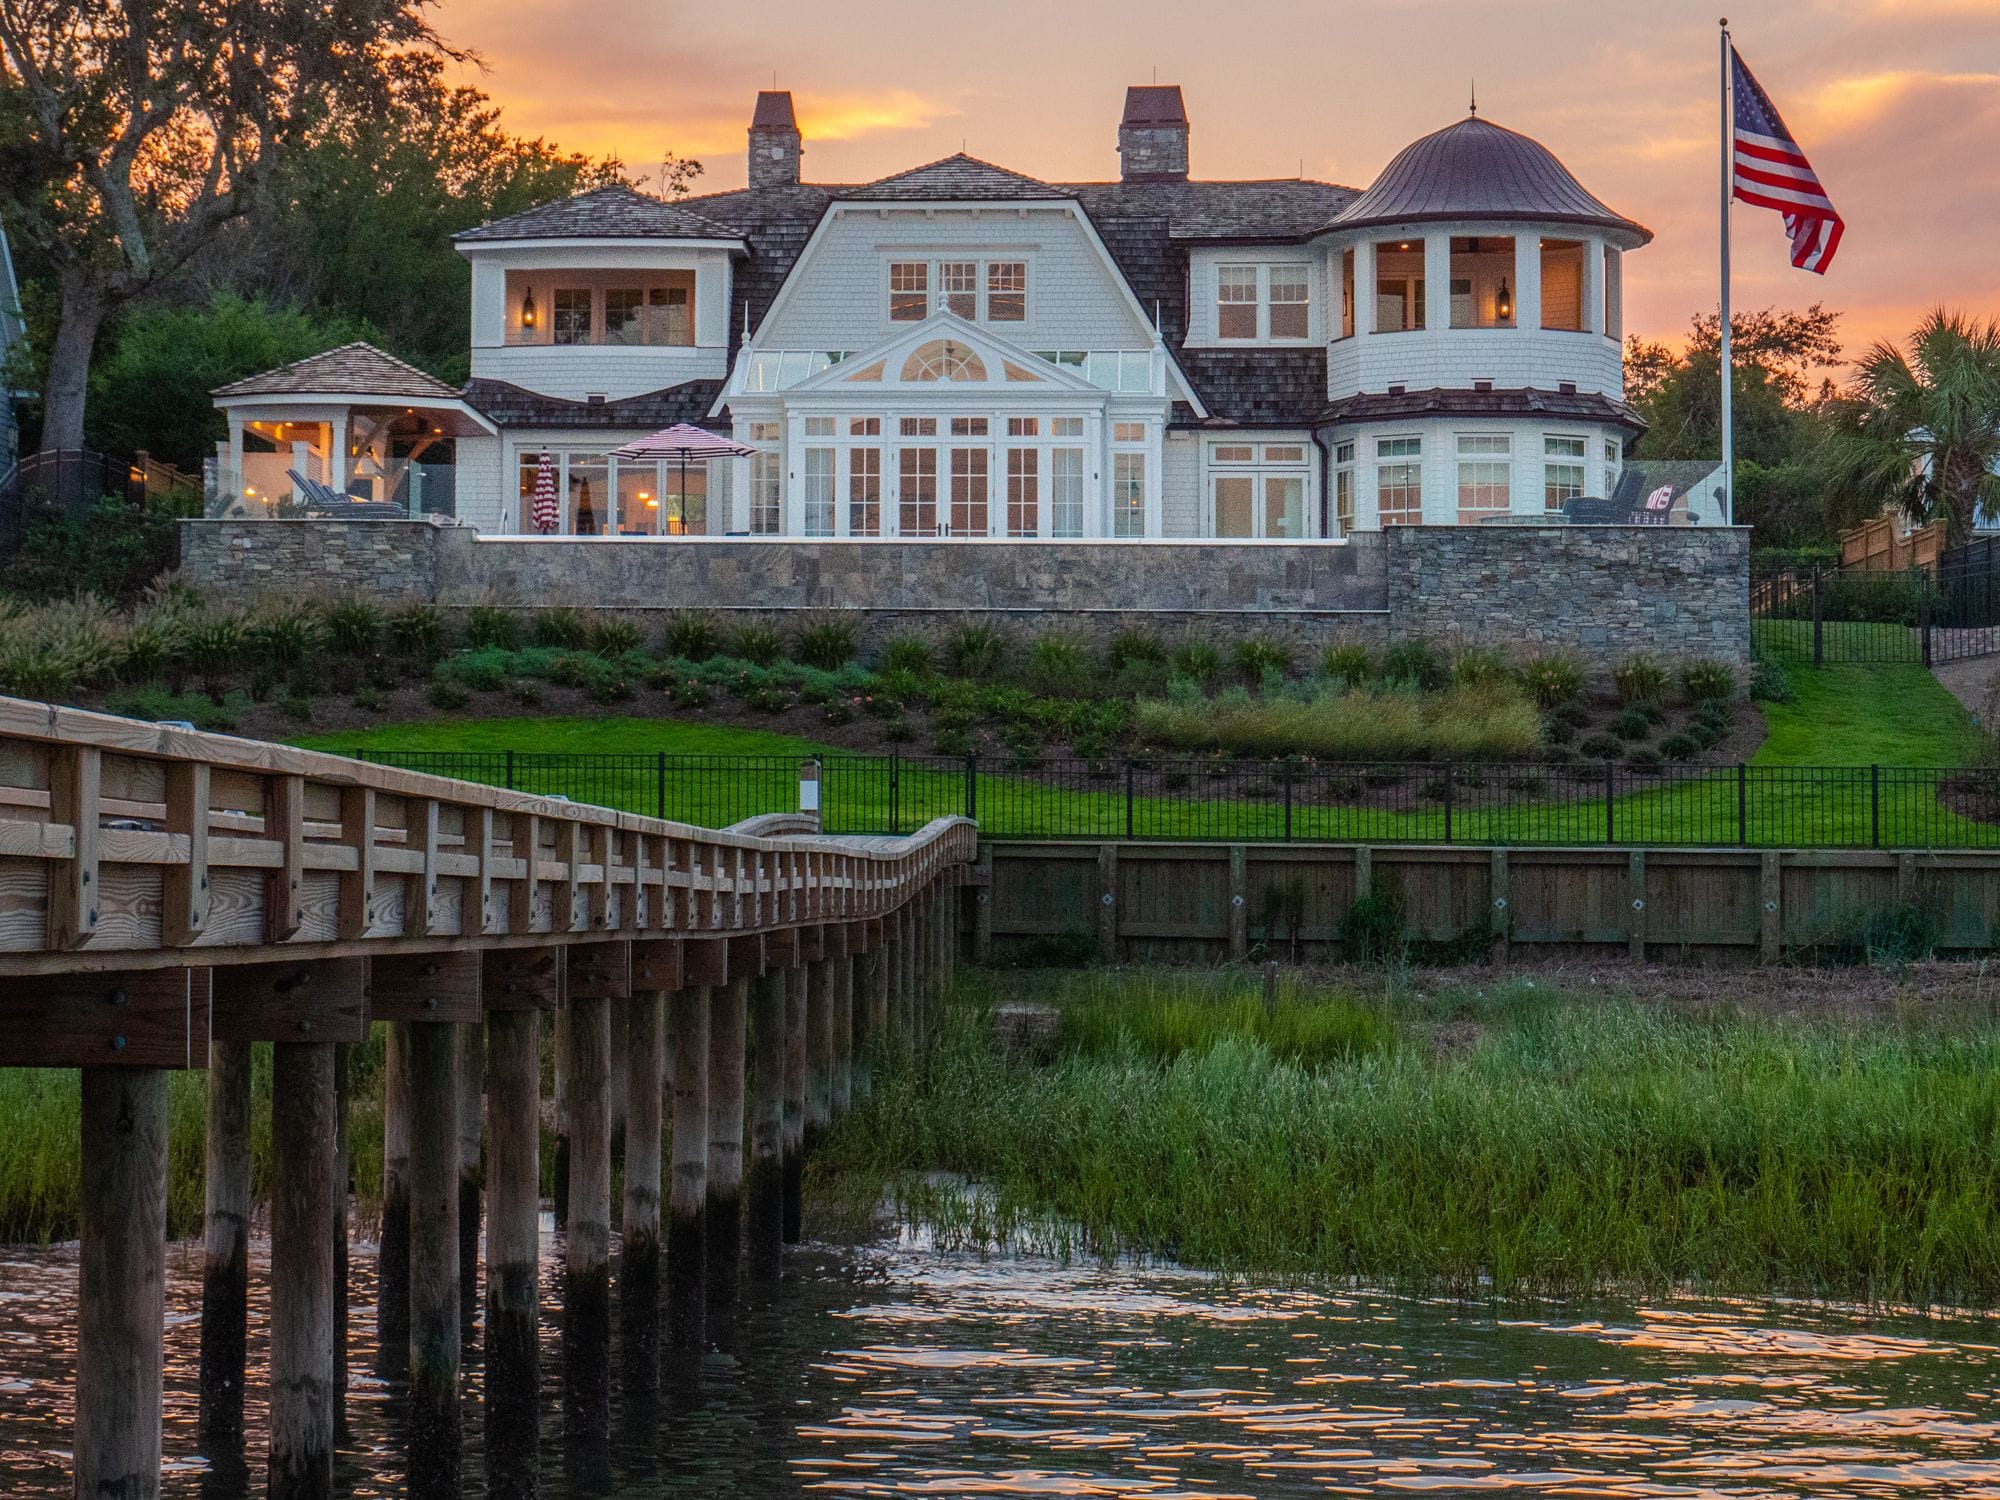
A waterfront home at Wilmington. Photo: Tongue & Groove Design + Build, CC BY-SA 4.0
What coastal home insurance covers
Not every carrier writes coastal property. Associates For Insurance Services works to identify available options based on your property's location, use, construction, and coverage needs. A coastal homeowners policy covers the structure, what is inside it, your liability as the owner and the cost of living elsewhere while a covered loss is repaired. On the Crystal Coast the questions that decide how a policy performs are how wind and hail are handled, what the deductibles are, and whether flood has been written as its own policy.
Why it matters
A policy that was never built for a coastal address can look fine on paper until a storm season tests it. The wind and hail deductible, the replacement cost basis and the exclusions are what matter in that week, and they are worth reading before the policy is bound rather than after.
Who it is for
Owners of a primary home, a second home or a rental property in Cedar Point, Cape Carteret, Emerald Isle, Swansboro, Morehead City, Atlantic Beach and the rest of coastal Carteret and Onslow counties.
Here, specifically
Carteret County has a wide variety of properties: homeowners, landlords, seasonal occupants, even those staying only one night. The North Carolina Department of Insurance is direct about the gap most coastal owners ask about: "Homeowners insurance policies do not cover flood damage." Flood is a separate policy, and we quote the two together.
What a policy can include
- Homeowners or property coverage
- Wind and hail protection
- Flood insurance options
- Replacement cost and deductibles
- Rental or vacation property use
How a quote goes
- 01
A conversation first
What you are protecting, how it is used, and what has changed since the last policy was written.
- 02
We look at the options available
Not every insurer writes every risk. We identify the options that fit the property, the vehicle or the business, and compare them.
- 03
We read for gaps
Deductibles, exclusions and limits, not just the headline number, so nothing surprises you later.
- 04
Plain English, zero pressure
We walk you through what each option does and leave the decision with you.
Questions we get about coastal home insurance
Does a homeowners policy on the Crystal Coast cover flood damage?
What do you need from me to quote a coastal home?
Information is general in nature and may not reflect your specific situation. Contact us for guidance on your own policy.
Let's talk about your coastal home insurance.
A conversation about what you have and what your options look like, with zero pressure.