Associates for Insurance Services
Home Insurance
Homeowners, renters and condo coverage across North Carolina, from new and high-value homes to the neighborhood houses of Jacksonville, Newport and Swansboro, plus builder's risk while a home is under construction.
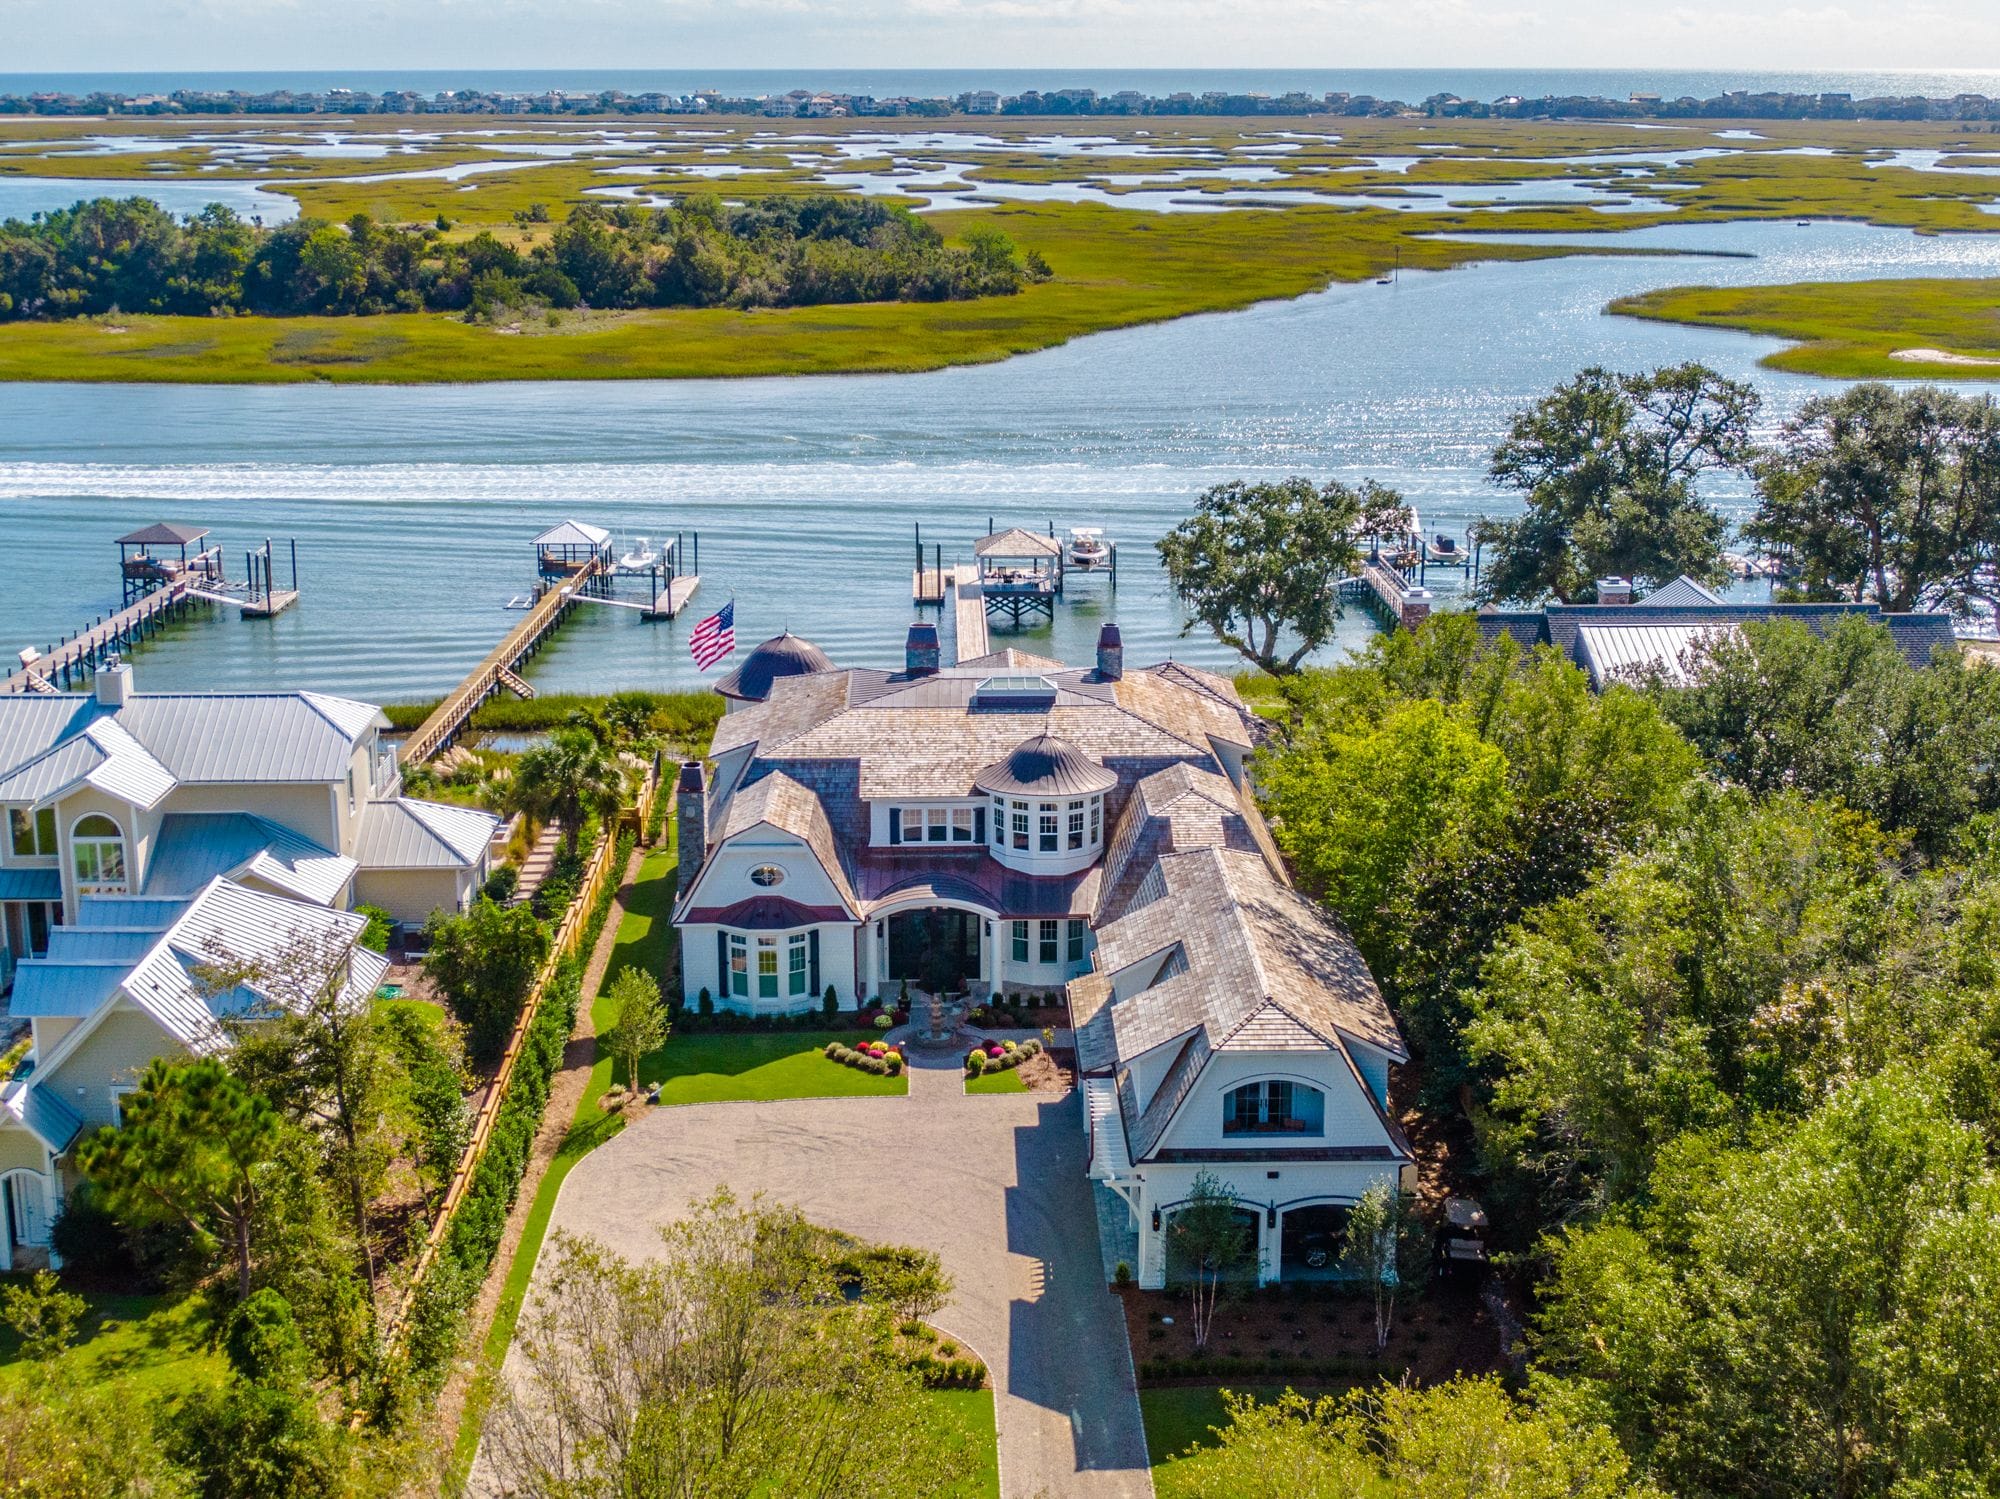
A waterfront home at Wilmington, from the air. Photo: Tongue & Groove Design + Build, CC BY-SA 4.0
What home insurance covers
A homeowners policy covers the house, the belongings inside it, your liability if someone is hurt on the property, and the cost of living elsewhere while a covered loss is repaired. Away from the beach the questions change: roof age, the age of the wiring and plumbing, and whether the dwelling limit would actually rebuild the house today. Renters and condo policies cover what a landlord's or association's policy does not. Builder's risk covers a home while it is under construction, from the foundation to the day the owner moves in. New and high-value homes, homes on golf courses and new homes on the beach are written with the replacement cost, the finishes and the location in mind.
Why it matters
Your mortgage company requires the policy, but the policy exists for you. Whether the dwelling limit matches today's cost to rebuild, and whether the deductible is one you could absorb, are the two answers that decide how a bad week turns out.
Who it is for
Homeowners, renters and condo owners across North Carolina and in South Carolina: new and high-value homes, homes on golf courses, new homes on the beach, and the neighborhood houses of Jacksonville, Newport, Swansboro, Cape Carteret and Morehead City. Owners building a home, who need builder's risk until it is finished. Buyers closing on a house anywhere in North Carolina, and the real estate agents and mortgage lenders who send them to us. Mobile homes and park models are written on their own forms; see that page.
Here, specifically
A neighborhood house in Newport and a brick ranch outside Jacksonville come with the same first questions: how old is the roof, how old are the wiring and plumbing, and what would it cost to rebuild today. Bring your current declarations page and we start there. If a car or two sits in the driveway, we look at the home and auto policies together.
What a policy can include
- Dwelling and other structures
- Builder's risk: insurance for homes under construction
- High-value homes: new and high-value homes, homes on golf courses, new homes on the beach
- Personal property
- Loss of use
- Personal liability and medical payments
- Renters (HO-4) and condo (HO-6) policies
- Scheduled jewelry, art and collections
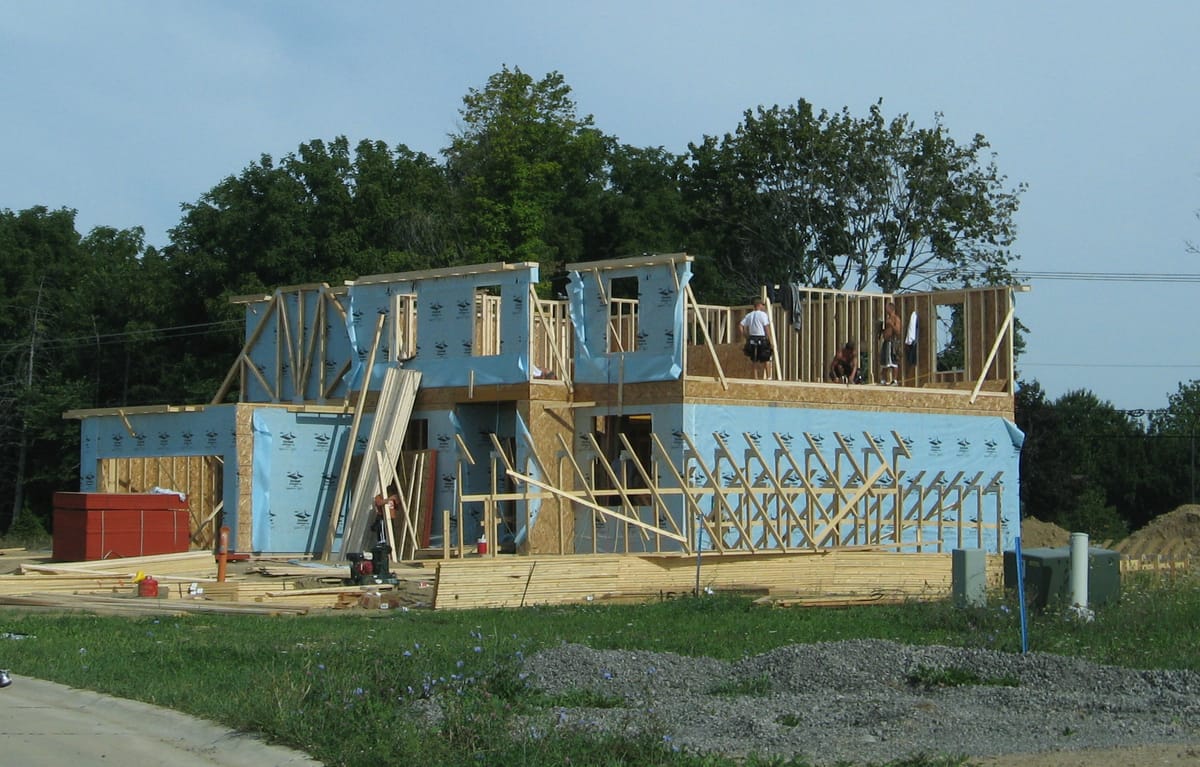
A new house going up in a subdivision. Photo: Dwight Burdette, CC BY 3.0
How a quote goes
- 01
A conversation first
What you are protecting, how it is used, and what has changed since the last policy was written.
- 02
We look at the options available
Not every insurer writes every risk. We identify the options that fit the property, the vehicle or the business, and compare them.
- 03
We read for gaps
Deductibles, exclusions and limits, not just the headline number, so nothing surprises you later.
- 04
Plain English, zero pressure
We walk you through what each option does and leave the decision with you.
Questions we get about home insurance
What is the difference between a renters policy and a homeowners policy?
Do you work with real estate agents and mortgage lenders?
Do you insure a home while it is being built?
Can you quote my home and my cars together?
Information is general in nature and may not reflect your specific situation. Contact us for guidance on your own policy.
Let's talk about your home insurance.
A conversation about what you have and what your options look like, with zero pressure.